
Updated Sustainability Reporting Rules: Filing Priorities and Timelines for Taiwan's Listed Companies (May 2026 Amendments)
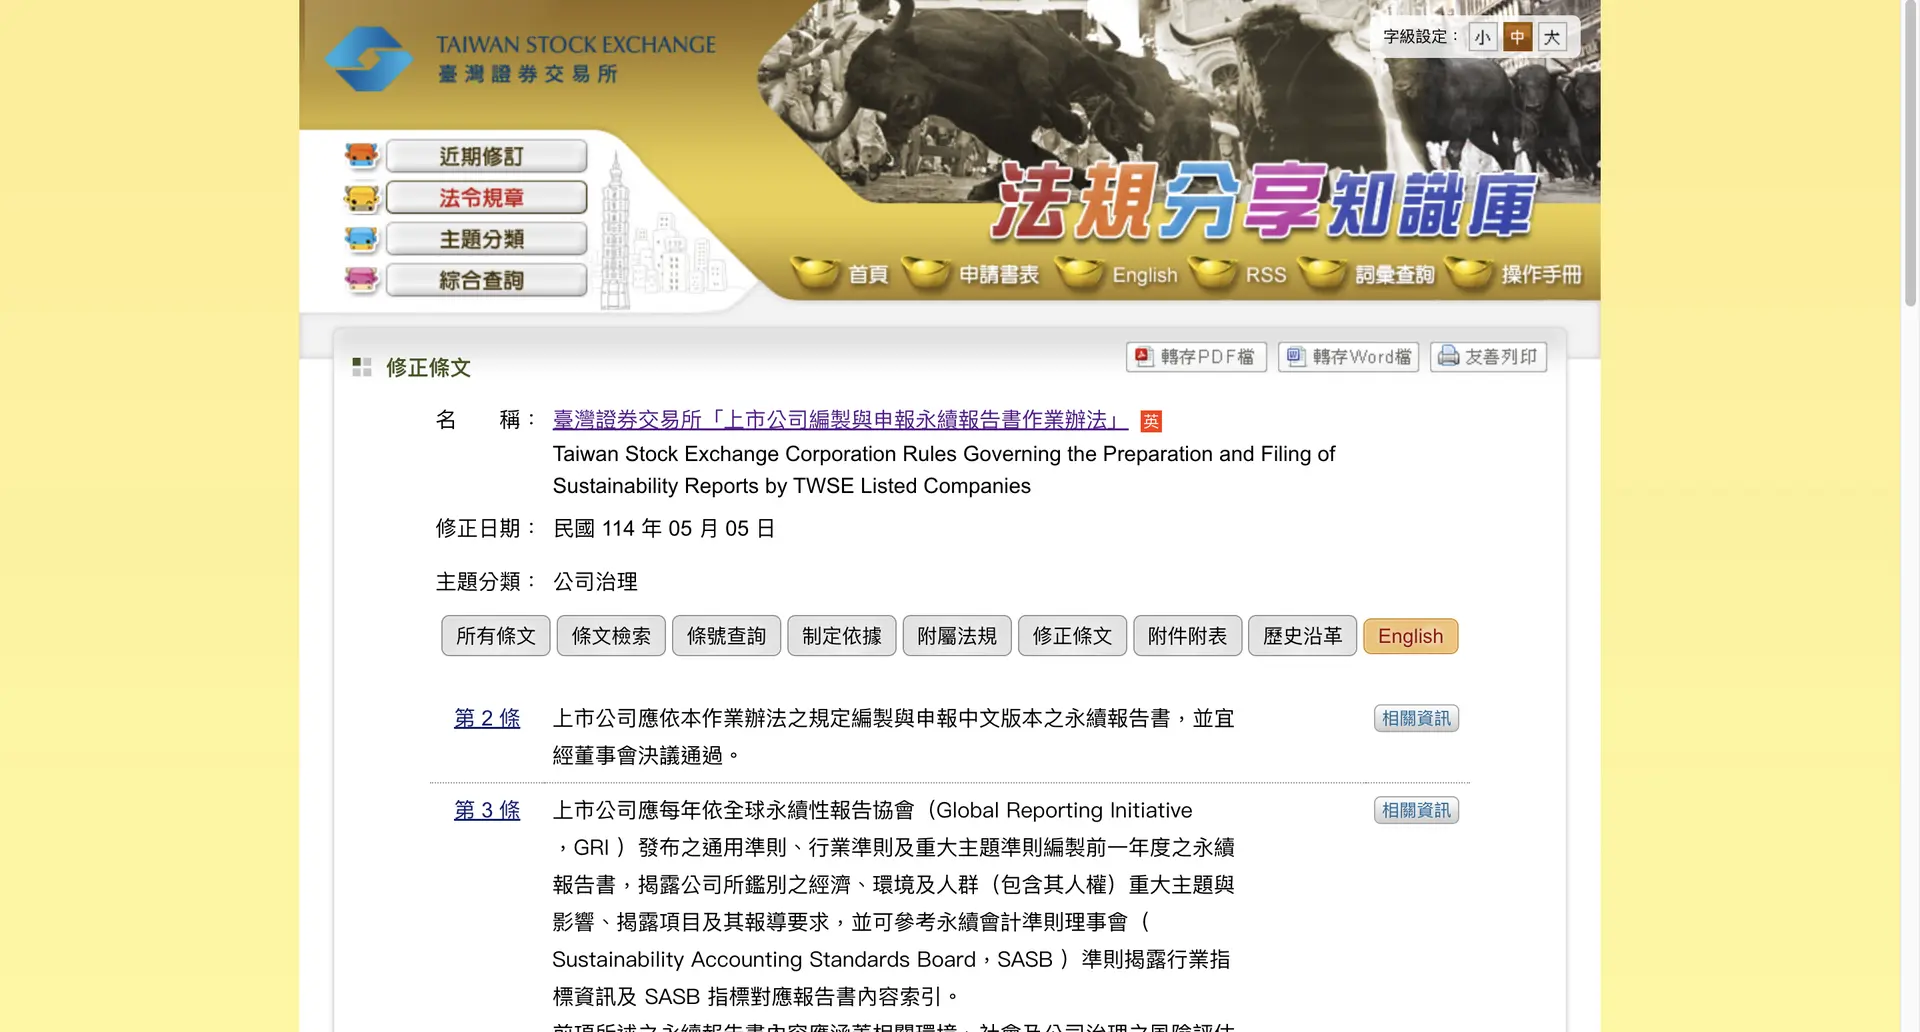
The Taiwan Stock Exchange announced the latest amendments to its Rules Governing the Preparation and Filing of Sustainability Reports by TWSE Listed Companies on May 18, 2026, following approval for recordation by the Financial Supervisory Commission on May 14, 2026. This article summarises the amendments and current filing requirements to help companies understand industry indicators, climate information, assurance and internal controls.
What to decide after reading If you came for IFRS, SASB, TCFD, GRI, or ESG reporting requirements, the next step is to turn disclosure items into data collection, section assignments, and review workflows.
Table of Contents
- Key Updates to the Reporting Rules
- 1. Disclose Salaries of Non-Managerial Employees
- 2. Prepare Reports "in Accordance with" GRI Standards
- Filing Requirements and Penalties
- May 2026 Amendments: Reducing Duplicate Disclosures after IFRS Adoption
- Further Reading: Other Sustainability Reporting Compliance Resources
Updated on October 6, 2026. This update adds the May 2026 amendments to the reporting rules and their conditions of application.
Key Updates to the Reporting Rules
1. Disclose Salaries of Non-Managerial Employees
Domestic TWSE-listed companies must disclose in their sustainability reports the average and median salaries of full-time non-managerial employees, together with the year-on-year changes in both figures. This information may be disclosed through a lookup reference to the information reporting website designated by the Exchange. — Article 4-2 of the Rules
Domestic TWSE-listed companies must at least provide a clear navigation path to the relevant disclosure page on the Market Observation Post System (either of the examples below may be used) to comply with the requirements.
Paths to salary disclosures for full-time non-managerial employees:
(1) Market Observation Post System > Summary Reports > Corporate Governance > Employee Benefits and Remuneration Statistics > Full-Time Non-Managerial Employee Salaries / Salary Information for Full-Time Employees Not in Managerial Positions
(2) Market Observation Post System > Individual Company > Corporate Governance > Corporate ESG > Corporate ESG Company Information > ESG Information Disclosure (Individual Company Search) > Social — Human Capital Development Indicators
2. Prepare Reports "in Accordance with" GRI Standards
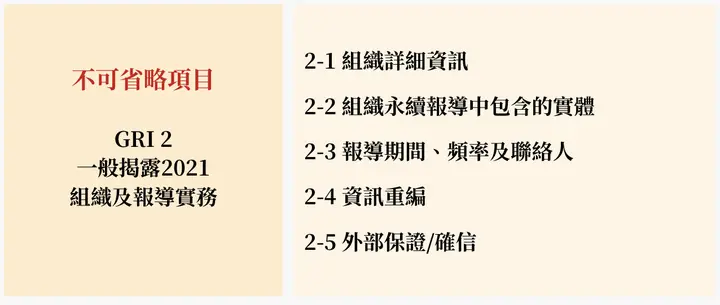
When preparing sustainability reports, companies must disclose GRI 2-1 through 2-30. GRI 2-1 through 2-5 cannot be omitted; reasons must be provided for omitting disclosures under GRI 2-6 through 2-30. Under GRI 3, companies must also disclose their process for determining material topics, the list of material topics and how those topics are managed.
Further reading:
Turn this article into your next step
If this article touches disclosure, carbon inventory, or report preparation, use the system or database to check how peers handle it.
Filing Requirements and Penalties
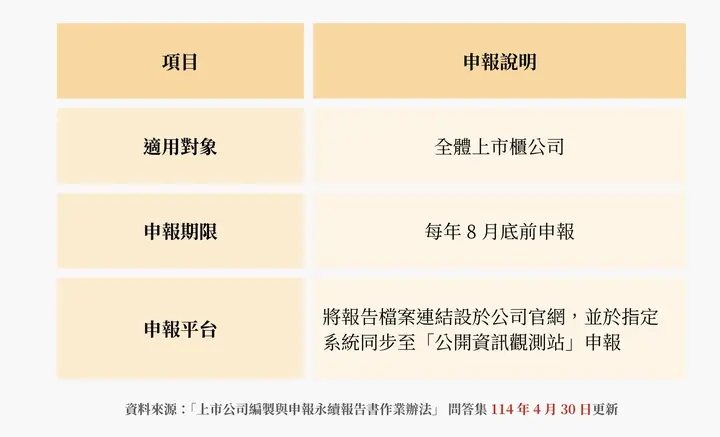
All TWSE/TPEx-listed companies must file their sustainability report and a link to the report file on their company website through the designated online information reporting system by the end of August.
If a TWSE-listed company fails to file its sustainability report within the prescribed deadline, or files information containing errors or omissions—for example, failing to prepare the report using GRI Standards as required—it may face penalties depending on the circumstances.
May 2026 Amendments: Reducing Duplicate Disclosures after IFRS Adoption
According to the amendment comparison table, a new paragraph 5 in Article 4 allows TWSE-listed companies that already apply IFRS Sustainability Disclosure Standards and disclose SASB industry metrics in their annual reports to be exempt from the industry sustainability indicator and assurance requirements in paragraphs 1 through 4. A new paragraph 6 in Article 4-1 allows companies that already apply the standards and disclose a dedicated sustainability-related financial information chapter in their annual reports to be exempt from paragraphs 1 through 5. Article 5 also reflects the renamed guidelines for managing assurance institutions and removes references to implementation years that have already passed.
These exemptions are conditional; they do not exempt all companies from preparing sustainability reports. Companies that do not meet the conditions must still disclose applicable industry indicators and obtain required assurance under Article 4, disclose climate information in a dedicated chapter under Article 4-1, and follow the phased greenhouse gas inventory and assurance timeline.
Filing by August 31 each year and incorporating report preparation and assurance into internal controls are existing requirements under Article 5, not new additions in this amendment. Salary disclosure and GRI requirements also continue to apply. Sources: May 18, 2026 amendment comparison table, Current reporting rules.
Further Reading: Other Sustainability Reporting Compliance Resources
- Q&A on the Rules Governing the Preparation and Filing of Sustainability Reports by TWSE Listed Companies, April 30, 2025 (ROC 114.04.30)
- Taiwan Stock Exchange: Rules Governing the Preparation and Filing of Sustainability Reports by TWSE Listed Companies
- Corporate Governance Center — Corporate ESG Information Disclosure
- IFRS Adoption Portal
- Chinese SASB Standards Now Available: Understanding the Latest SASB Standards and Reporting Requirements
GRI Standards Materiality Analysis Sustainability Report Guidelines
FAQ
View AllWhat are the key May 2026 amendments to the sustainability reporting rules?
Companies that already apply IFRS Sustainability Disclosure Standards and disclose SASB industry metrics or a dedicated sustainability-related financial information chapter in their annual reports may be exempt from certain duplicate disclosure requirements under Article 4, paragraph 5 and Article 4-1, paragraph 6, respectively. Article 5 also reflects the renamed assurance institution management guidelines and removes past implementation-year references. The annual August 31 filing deadline and internal control requirements remain applicable.
Which GRI Standards must TWSE-listed companies follow when preparing sustainability reports?
When preparing sustainability reports, TWSE-listed companies must disclose GRI 2-1 through 2-30. GRI 2-1 through 2-5 cannot be omitted, while reasons must be provided for omitting disclosures under GRI 2-6 through 2-30. Companies must also disclose the process for determining material topics and their management under GRI 3.
What is the sustainability report filing deadline?
All TWSE/TPEx-listed companies must file their sustainability reports and links to the relevant files on their company websites through the designated online information reporting system by the end of August. Late filings or errors in reported information may result in penalties.
Turn Sustainability Disclosure into a Collaborative Workflow
Use Syber to manage section ownership, metric data, review records, and disclosure progress, turning IFRS, SASB, and GRI requirements into a team workflow.
How to decide the next stepTurn the disclosure requirements in the article into sections, data sources, and owners first. If collaboration, version control, or verification is involved, then evaluate whether a reporting workflow is needed.