
GRI 102 & 103 Update (2027): Climate & Energy Disclosure Changes Explained
Sustainability reporting disclosure is moving from compliance to substantial governance management disclosure. With the release of the latest GRI Standards provisions in June 2025, including GRI 102 'Climate Change 2025' and GRI 103 'Energy 2025', companies must face more detailed disclosure requirements, from just transition, climate adaptation, to enhanced Scope 3 emission information transparency. This update is not just about changes in provisions, but a restructuring of organizational internal governance logic. This article will help you understand the background of GRI standards updates, key changes in GRI 102 and GRI 103, and where companies should start preparing to respond to the latest standards.
What to decide after reading If you came for IFRS, SASB, TCFD, GRI, or ESG reporting requirements, the next step is to turn disclosure items into data collection, section assignments, and review workflows.
Table of Contents
- Sustaihub Key Takeaways
- History of GRI and Purpose of Disclosure Requirements
- GRI 102 "Climate Change 2025" Core Highlights
- 🌍 Climate Adaptation and Transition Actions
- Our consulting team has compiled the following key additions:
- 🟡 GRI 102-3 Just Transition
- 🟡 GRI 102-10 Carbon Credit
- How is GRI 102 Climate Change Different from TCFD Framework?
- GRI 103 "Energy 2025" Core Highlights
- Topic Management Disclosures
- Topic Disclosures
- When Do GRI 102 and GRI 103 Take Effect?
- Conclusion
- Extended Reading
Sustaihub Key Takeaways
- GRI 102: Climate Change 2025 and GRI 103: Energy 2025 take effect on January 1, 2027.
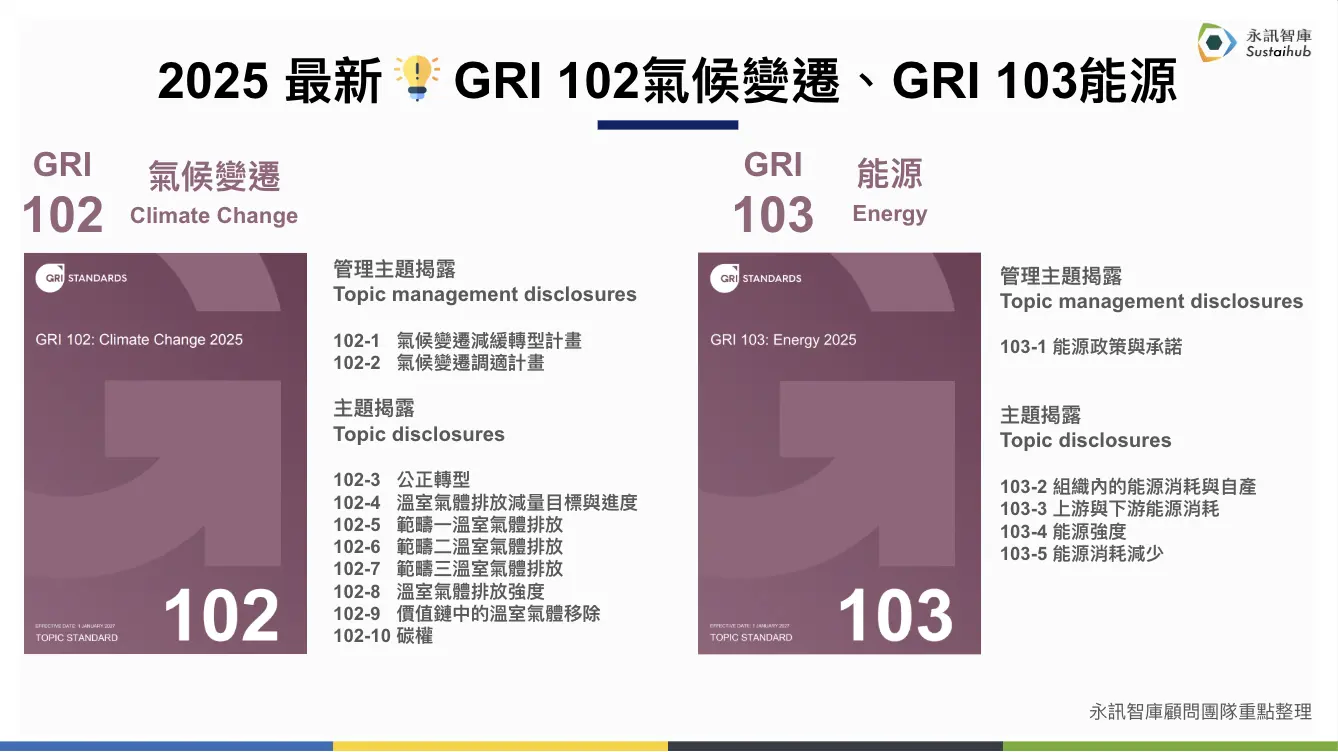
- GRI 102 adds disclosures including 102-3 Just Transition (protecting workers' rights, and dialogue with and compensation for communities and Indigenous Peoples) and 102-10 Carbon Credits (management, planning and communication of purchases, trading and offsets).
- GRI 103 uses 103-1 Energy Policies and Commitments as its topic management disclosure; its topic disclosures cover energy consumption and self-generation within the organization, upstream and downstream energy consumption, energy intensity, and reduction of energy consumption. Compared with GRI 302, it places greater emphasis on governance strategy, accountability, target setting and progress tracking.
- Topic disclosures in the new standards do not replace the GRI 3-3 Management Approach Disclosure; the two must be used together. TCFD and GRI 102 are also not mutually exclusive frameworks.
Sustaihub compiled 2025 ESG information disclosure open data from the Taiwan Stock Exchange (TWSE, 證交所) and Taipei Exchange (TPEx, 櫃買中心), covering 1,962 TWSE/TPEx-listed companies (individual reports are available in the Sustaihub sustainability report database): companies reporting a renewable energy usage rate above 0 account for 26.5% of the 1,962 companies, and the median among the 702 reporting companies is 1.6%. When preparing GRI 103 energy policy and target disclosures, companies can use these figures to see where their own renewable energy usage rate stands among listed companies.
History of GRI and Purpose of Disclosure Requirements
The Global Reporting Initiative (GRI), established in 1997, has been dedicated to promoting corporate disclosure of their material impacts on the economy, environment, and society (ESG). After launching the GRI Standards modular framework in 2016, disclosure requirements became more flexible and systematic. In 2021, GRI released new Universal Standards (GRI 1, 2, 3), strengthening materiality assessment and governance responsibility disclosure.
In 2024, GRI 101 Biodiversity was released (effective in 2026), responding to global nature-related disclosure trends; in 2025, GRI 102 and GRI 103 were released, further raising the bar for climate and energy governance.
GRI's core purpose is to help companies clearly explain to all stakeholders (employees, communities, supply chains, investors, etc.) "how the company impacts society and the environment," and guide companies to comprehensively fulfill their responsibilities from strategy, governance to performance.
Turn this article into your next step
If this article touches disclosure, carbon inventory, or report preparation, use the system or database to check how peers handle it.
GRI 102 Climate Change & GRI 103 Energy Provisions at a Glance

GRI 102 "Climate Change 2025" Core Highlights
🌍 Climate Adaptation and Transition Actions
The new GRI 102 not only emphasizes emission data disclosure but also focuses on companies' adaptation plans and governance mechanisms, explaining how to reduce climate impacts and practical implementation steps.
Our consulting team has compiled the following key additions:
🟡 GRI 102-3 Just Transition
Requires disclosure of how companies protect workers' rights during climate transition, engage in dialogue and compensation with local communities and indigenous peoples, and strengthen protection of vulnerable groups.
🟡 GRI 102-10 Carbon Credit
Disclose how companies manage, plan and communicate carbon credit purchases, trading, and offsets, and explain their impact on overall carbon management strategy.
How is GRI 102 Climate Change Different from TCFD Framework?
When it comes to climate change information disclosure, most companies currently disclose climate information primarily following TCFD (Task Force on Climate-related Financial Disclosures), which aims to help investors and financial markets understand the impact of climate risks on corporate finances. According to FSC requirements, Taiwan listed companies need to disclose climate-related information in their annual reports.
GRI 102: Climate Change 2025 focuses on how companies take action from both mitigation and adaptation perspectives, explaining the actual impacts and response measures on external factors (human rights, society, environment).

Comparison table of GRI 102 Climate Change and TCFD Climate-related Financial Disclosure (Compiled by Sustaihub)
TCFD and GRI 102 are not mutually exclusive frameworks. TCFD can be used for risk disclosure in financial reports to explain climate-related financial information to investors; while GRI 102 can be part of sustainability reports, explaining corporate sustainability practices, responsibility fulfillment, and interaction with stakeholders. Using both together provides a more complete climate information perspective "from internal corporate risks to external impact management."
GRI 103 "Energy 2025" Core Highlights
The new GRI 103 strengthens energy governance and strategy disclosure, with key provisions as follows:
Topic Management Disclosures
- 103-1 Energy Policy and Commitments: Explains the organization's policies on energy efficiency, renewable energy adoption, decarbonization commitments, and target setting.
Topic Disclosures
- 103-2 Energy consumption and self-generation within the organization
- 103-3 Upstream and downstream energy consumption
- 103-4 Energy intensity
- 103-5 Reduction of energy consumption
Compared to GRI 302 Energy: 2016, GRI 103 places greater emphasis on adding governance strategy, responsibility attribution, target setting, and progress tracking
When Do GRI 102 and GRI 103 Take Effect?
According to GRI official announcement, the following standards will officially take effect on January 1, 2027:
🆕 GRI 102: Climate Change 2025
🆕 GRI 103: Energy 2025
⚠️ These topic disclosures do not replace the existing GRI 3-3 Management Approach Disclosure, but serve as supplements and should be used together.
Conclusion
The updates to GRI 102 and 103 make sustainability reports no longer just about information disclosure, but a concrete demonstration of how companies actually manage core issues such as climate change, energy transition, and biodiversity. Report content will be more rigorous, symbolizing ESG management entering a new phase.
To stay updated on the latest sustainability disclosure trends, click Sustaihub for the latest news.
Extended Reading
FAQ
View AllWhen do GRI 102 and GRI 103 take effect?
According to GRI’s official announcement, GRI 102: Climate Change 2025 and GRI 103: Energy 2025 will take effect on 1 January 2027. These topic disclosures do not replace the existing GRI 3-3 disclosures on management approaches; they complement them and should be used together.
How does GRI 102 require companies to protect workers’ rights during the climate transition?
GRI 102-3 Just Transition requires companies to disclose how they protect workers’ rights during the climate transition, engage in dialogue with local communities and Indigenous Peoples, and provide compensation, strengthening protection for vulnerable groups.
How do GRI 102 and the TCFD framework differ in climate disclosure?
GRI 102: Climate Change 2025 focuses on companies’ actions from both mitigation and adaptation perspectives, explaining their actual impacts on external factors (human rights, society and the environment) and their responses. TCFD primarily helps investors and financial markets understand the financial effects of climate risks on companies.
Turn Sustainability Disclosure into a Collaborative Workflow
Use Syber to manage section ownership, metric data, review records, and disclosure progress, turning IFRS, SASB, and GRI requirements into a team workflow.
How to decide the next stepTurn the disclosure requirements in the article into sections, data sources, and owners first. If collaboration, version control, or verification is involved, then evaluate whether a reporting workflow is needed.