
Strengthening Sustainability Information Controls: Meeting New Rules and Building Competitiveness
How should companies respond to new sustainability information control requirements? From establishing controls to integrating audit plans, ensure compliant sustainability information and strengthen competitiveness.
What to decide after reading If you are still researching, first confirm whether your task is the report, the carbon inventory, peer disclosure references, or software selection.
Table of Contents
Updated on 6 October 2026. Standardised the effective date for sustainability information controls and added changes to mandatory IFRS adoption scope.
As IFRS Sustainability Disclosure Standards (ISSB Standards) are introduced progressively, corporate Sustainability Information Internal Control (SIIC) has shifted from an optional practice to a mandatory requirement. On 22 April 2024, the Financial Supervisory Commission (FSC) amended the Regulations Governing Establishment of Internal Control Systems by Public Companies. The relevant provisions took effect on 1 January 2025, requiring TWSE/TPEx-listed companies to include sustainability information management in their internal controls and internal audit plans. This change increases disclosure transparency and raises standards for financial information integration, internal process improvement and corporate risk management.
For companies, the new requirements involve more than formal adjustments: they require a systematic effort covering cross-department collaboration, data management, internal control reviews and compliance risk prevention. How can companies ensure accurate disclosure, strengthen controls for IFRS Standards and use internal audits to improve sustainability information management? This article explains how to introduce and improve sustainability information controls progressively, ensuring compliance and strengthening competitiveness.
Turn this article into your next step
If this article touches disclosure, carbon inventory, or report preparation, use the system or database to check how peers handle it.
Legal basis: Articles 8, 13 and 47 of the Regulations Governing Establishment of Internal Control Systems by Public Companies.
Global Sustainability Information Management: From Regulation to Competitiveness
Major economies have actively standardised sustainability information management in recent years to improve disclosure transparency and consistency. These rules require compliance and also influence market valuations and trust.
- IFRS Sustainability Disclosure Standards (ISSB S1 & S2): Global standards requiring financially relevant sustainability disclosures that are auditable and comparable.
- EU Corporate Sustainability Reporting Directive (CSRD): Requires disclosure based on both impact materiality and financial materiality, with third-party verification of sustainability reports.
- Taiwan FSC amendments to internal control regulations: Relevant provisions amended on 22 April 2024 took effect on 1 January 2025. TWSE/TPEx-listed companies must include sustainability information management in internal controls and annual audit plans.
These trends show that sustainability information has become more than a compliance requirement: it is an important indicator of governance, financial decision-making and market competitiveness. Companies that prepare early and establish robust controls can gain an advantage in sustainable finance markets and attract institutional investors.
Corporate Challenges and Pain Points
1. Establishing and Adjusting Sustainability Information Controls
The new rules require TWSE/TPEx-listed companies to establish sustainability information controls, but many face these challenges:
- Incomplete controls: Existing frameworks focus on financial and operational risks and lack effective controls over ESG information.
- Difficult cross-department collaboration: Sustainability information spans legal, finance, supply chain and ESG teams, making integration complex.
- Growing audit and compliance pressure: Companies must submit their sustainability information control frameworks to the board for review to ensure regulatory compliance.
2. Implications of IFRS Sustainability Disclosure Adoption
From 2026, TWSE/TPEx-listed companies with capital of NT$10 billion will be the first to adopt IFRS Sustainability Disclosure Standards. Under the FSC and Ministry of Environment's 23 September 2026 adjustment proposal, approximately 560 listed companies face mandatory adoption. Companies with paid-in capital below NT$2 billion and no Ministry of Environment-regulated sources requiring inventory and verification are exempt, but must disclose basic climate information. Financial, insurance, and securities and futures businesses follow separate rules. Actual applicability is subject to regulations formally issued by the authorities. See IFRS Phase 3 Adjustment and the FSC announcement. These changes place the following pressures on internal data management and reporting:
- Higher data quality requirements: Sustainability information must be consistent with financial data and be traceable and verifiable.
- Improved internal control processes: Companies must review sustainability data collection, verification and reporting to ensure appropriate oversight and review mechanisms support accurate disclosure.
3. Sustainability Information Controls Across Corporate Groups
Groups with multiple subsidiaries face more complex management challenges:
- Cross-border compliance pressure: Subsidiaries must meet both local laws and parent-company standards, increasing management complexity.
- Consistency of controls: Separate subsidiary control processes may create inconsistent sustainability information standards and undermine group-wide disclosure quality.
How Can Companies Strengthen Sustainability Information Controls?

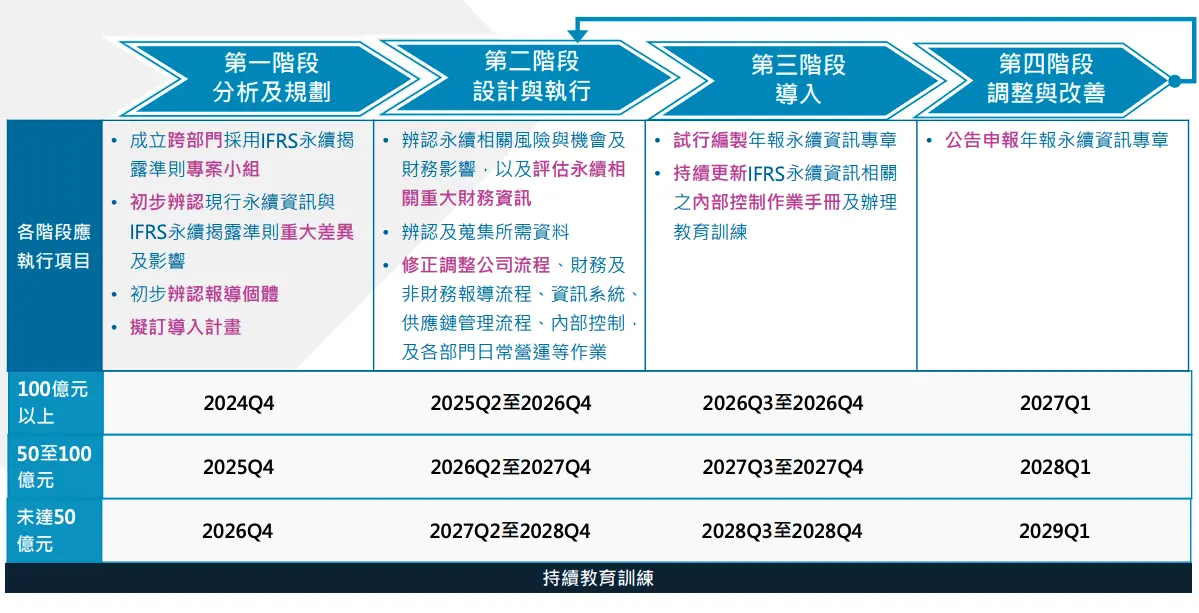
Adopting IFRS Sustainability Disclosure Standards requires both compliance and controls that can operate sustainably, ensuring accurate, reliable information. Under the Regulations Governing Establishment of Internal Control Systems by Public Companies, the FSC reminds TWSE/TPEx-listed companies that from 1 January 2025 they must establish internal controls for sustainability information management and include them in audit plans, referring to the control reference items published by the Taiwan Stock Exchange (TWSE) and Taipei Exchange (TPEx) to adjust management mechanisms on an ongoing basis. Companies can take the following actions at each stage:
1. Establish a Strong Internal Control Framework
- Form a project team: Bring finance, ESG, information systems and other functions together in a cross-department team, with the board overseeing progress.
- Identify material differences and impacts: Compare current sustainability information against IFRS Sustainability Disclosure Standards and assess financial reporting implications to develop effective control strategies.
- Define the reporting entity and adoption plan: Set reporting boundaries aligned with consolidated financial statements and develop a detailed, feasible implementation plan.
2. Introduce Sustainability Information Control Processes
- Identify key risks and opportunities: Assess how sustainability risks affect corporate finances and establish internal review mechanisms to ensure complete disclosure.
- Adjust internal processes: Revise financial and non-financial information collection, supply chain management and internal control activities to meet IFRS Sustainability Disclosure Standards.
- Establish data management and internal audit mechanisms: Ensure data sources, calculation methods and reporting processes meet internal control standards and are included in the annual audit plan.
3. Trial and Improve
- Trial the annual report sustainability section: Prepare a preliminary section under IFRS Sustainability Disclosure Standards to test disclosure applicability and completeness.
- Continuously improve controls: Use internal testing and performance assessments to refine processes and audit mechanisms, ensuring accurate disclosure.
- Train all staff: Regularly provide training on IFRS sustainability information controls so each department understands control standards and disclosure requirements.
Recommended Actions and Outlook

Short-Term Actions (Within 1 Year): Establish Controls and Compliance Foundations
- Form a cross-department team and launch the IFRS Sustainability Disclosure Standards adoption plan.
- Identify material differences between sustainability and financial information, ensuring consistent reporting boundaries and controls.
- Establish control processes and data management mechanisms, incorporating them into internal audit plans to ensure accurate, verifiable information.
Medium-Term Actions (Within 1–3 Years): Trial Implementation and Improve Audits
- Trial the annual report sustainability section to verify the applicability of IFRS Sustainability Disclosure Standards.
- Assess and adjust controls to ensure strong consistency between financial and sustainability information.
- Strengthen risk management and oversight of supply chain information, connecting internal and external data effectively.
Long-Term Actions (Beyond 3 Years): Comprehensive Improvement and Strategic Integration
- Integrate sustainability information controls closely with business strategy so they become part of decision-making.
- Keep internal control manuals current and institutionalise training, embedding a control culture throughout the company.
- Review and adjust regularly in response to international trends and regulatory changes to maintain competitiveness and compliance.
Use Information Technology to Improve Sustainability Reporting Quality and Efficiency
IFRS Sustainability Disclosure Standards have become a new corporate benchmark. Early preparation and stronger controls are essential to compliance and competitiveness. Sustaihub's digital sustainability consulting team is committed to finding effective ways to achieve corporate sustainability management goals.
Sustaihub's Syber sustainability management system offers three key features to help ensure information accuracy:
- Activity histories, review workflows and multi-level access controls: Improve data reliability
- Cross-department consolidation to resolve fragmented data: Accelerate data integration
- Automated project management and AI collaboration: Reduce staff workloads
Syber helps companies achieve compliance and improve internal efficiency without extensive staff time. With comprehensive support for sustainability, it is an ideal collaboration platform for sustainability reporting.
References:
- FSC Reminds Listed Companies to Establish Internal Controls for Sustainability Information Management – Financial Supervisory Commission website, 2025/01/16
- Internal Control Practices for IFRS Sustainability Disclosure Standards – TWSE Corporate Governance Center, 2024/08/27
- Accountants on Current Affairs: Strengthening Sustainability Information Controls – UDN, 2024/11/15
FAQ
View AllWhen did the FSC require companies to include sustainability information management in internal controls?
The FSC amended the Regulations Governing Establishment of Internal Control Systems by Public Companies on 22 April 2024, with relevant provisions taking effect on 1 January 2025. TWSE/TPEx-listed companies must include sustainability information management in internal controls and annual audit plans.
What are the main challenges in introducing sustainability information controls?
Key challenges include incomplete control systems, difficult cross-department collaboration and growing audit and compliance pressure. Companies must adjust their control frameworks to meet the new regulatory requirements.
How can companies ensure accurate and reliable sustainability information?
Companies need strong control frameworks, cross-department project teams and board oversight of progress. They should identify material differences and impacts, define the reporting entity and establish an adoption plan to ensure accurate, reliable sustainability information.
Choose the ESG task you want to complete first
Still researching? See how peers write in the report database, or compare Syber and DCarbon.
How to decide the next stepStart by deciding what you need: an answer, regulations, peer examples, or a tool?