
Taiwan Carbon Credits: Trading, Prices and a 10% Carbon Fee Example
In Taiwan, carbon credits usually refer to recognized reduction credits. From credit origins, official trading channels and historical listing prices to the 10% deduction cap and conversion ratios in the Regulations Governing the Collection of Carbon Fees, work out step by step where the credits you buy can actually be used.
What to decide after reading If you came for emission factors, ISO 14064, CBAM, or carbon data, the next step is to check whether activity data, emission factor versions, and supporting evidence can be traced.
Table of Contents
- Carbon Credits, Emission Allowances, Carbon Fees and Carbon Taxes: What Each Term Means
- Where Credits Come From: Project Approval and Quality Criteria
- Where to Buy: Official Channels and Trading Process
- Reading Prices: NT$2,500–4,000 Is a Historical Listing Price
- Carbon Fee Example: How Much Can Be Deducted from 12,000 Tonnes of Chargeable Emissions?
- Uses Beyond the Carbon Fee: EIA Incremental Offsets and Carbon Neutrality
In Taiwan, carbon credits (碳權) usually mean reduction credits: credits issued under a recognized mechanism that represent greenhouse gas reductions and can be transferred and used in accordance with the rules. They are not a right to emit freely, nor a receipt that offsets the carbon fee once paid for. The sections below follow a credit from origin to trading, pricing and use, and estimate how much domestic credits can deduct from chargeable emissions, so you can judge whether a quote you have received actually meets your needs.
Carbon Credits, Emission Allowances, Carbon Fees and Carbon Taxes: What Each Term Means
Article 3 of the Climate Change Response Act (氣候變遷因應法) defines "reduction credits" and "emission allowances" separately, with reduction credits covering voluntary reduction, offset and early-action projects. Reduction credits represent recognized reduction outcomes; emission allowances are permits to emit under a cap-and-trade system, so the two have different origins. What people in Taiwan commonly call carbon credits usually refers to the former, and reduction credits are the focus here as well.
Carbon fees and carbon taxes, by contrast, are levy mechanisms. A carbon fee is a charge levied by law on qualifying emission sources, as defined in Article 2 of the Regulations Governing the Collection of Carbon Fees (碳費收費辦法); a carbon tax prices carbon emissions through the tax system. For carbon pricing concepts such as carbon taxes and emissions trading, see the World Bank's carbon pricing overview. In other words, paying the carbon fee does not give you carbon credits, and the per-tonne price of a credit is not the same as the carbon fee rate. If a document simply says "carbon credits", ask the provider to list the issuing scheme, project name, credit type, vintage and serial numbers so that discussions of price and use start from a common basis.
Where Credits Come From: Project Approval and Quality Criteria
Domestic reduction credits must be obtained through the applicable project scheme. They originate from voluntary reduction projects, offset projects or early-action projects and go through application, quantification and review. Energy saving can be a reduction measure, but lower electricity use or a completed corporate inventory does not automatically become tradable credits. If you want to develop a reduction project, methods and procedures are available on the Ministry of Environment (環境部) Voluntary Reduction and Offset Information Platform (自願減量暨抵換資訊平台), and credit management information is on the Ministry of Environment Reduction Credit Management System (減量額度管理系統).
From a buyer's perspective, "the project appears to have environmental benefits" and "the credits meet the conditions for use" are two different checks. Under the Ministry of Environment's Guidelines for Corporate Carbon Neutrality Claims (企業宣告碳中和指引), credits and projects used for carbon neutrality should meet criteria such as authenticity, uniqueness, no double counting, additionality and permanence. Additionality asks whether the reduction goes beyond what is already required by law or would have happened anyway.
Where to Buy: Official Channels and Trading Process
The Taiwan Carbon Solution Exchange (臺灣碳權交易所) officially opened on August 7, 2023, according to the Taiwan Stock Exchange (臺灣證券交易所) introduction, and a Ministry of Environment announcement in October 2024 confirmed that public trading of domestic reduction credits had begun. There are two channels: the exchange's official website provides separate entry points for domestic and international credit trading, while the Ministry of Environment's Reduction Credit Management System manages holdings, trading applications and use of domestic credits. To look up individual projects, start with the public listing of domestic credits and the credit marketplace.
Turn this article into your next step
If this article touches disclosure, carbon inventory, or report preparation, use the system or database to check how peers handle it.
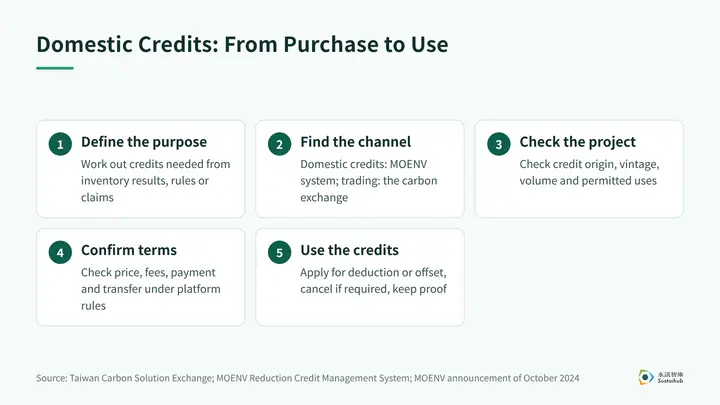
The sequence in the diagram is a way to prepare before purchasing; specific documents and steps follow each platform's current instructions. The records kept at each step, including the calculation of required volume, application conditions, project descriptions and issuance records, quotes and transaction documents, and transfer, cancellation and filing certificates, will later serve as the basis for applying for deductions or explaining your position externally.
Reading Prices: NT$2,500–4,000 Is a Historical Listing Price
There is no single carbon credit price in Taiwan that applies to every project. On October 21, 2024, the Ministry of Environment announced that the first 6 projects had listed a total of 6,080 tonnes of carbon dioxide equivalent, priced between NT$2,500 and NT$4,000 per tonne (listing volume and prices at the time). These figures are listing data from that time, not total traded volume, an average transaction price, or the current price in 2026. On the Taiwan Carbon Solution Exchange's domestic credit platform in October 2026, for example, projects listed for fixed-price trading were priced at NT$3,000 to NT$4,000 per tonne, and cumulative fixed-price transactions totaled 5 trades for 69 tonnes. The market is still small, so check the platform's current information before relying on any quote.
When comparing quotes, the price per tonne is only one column. Two quotes with the same per-tonne price may serve different purposes if the credit type or usable years differ. For budgeting, list the credit unit price, related service fees, deductible share and the carbon fee rate applicable to your company in separate columns; the price per tonne of credits and the carbon fee per tonne cannot be compared directly. For background on international markets, see "5 Trends in International Carbon Markets: ICAP ETS Report" and "Carbon Market Systems Around the World Explained".
Carbon Fee Example: How Much Can Be Deducted from 12,000 Tonnes of Chargeable Emissions?
Domestic credits can be used to apply for a deduction from the carbon fee's chargeable emissions; the purchase amount cannot be used directly to pay the fee. Articles 9 to 11 of the Regulations Governing the Collection of Carbon Fees cap domestic credit deductions at 10% of chargeable emissions and set different conversion ratios by credit origin.
| Credit origin | Emissions deductible per unit of credit | Additional conditions |
|---|---|---|
| Voluntary reduction or offset project credits | 1.2 | Still subject to the domestic credit deduction cap |
| Early-action project credits: businesses not at high carbon leakage risk | 0.3 | Usable only in the first three years after the carbon fee takes effect |
| Early-action project credits: recognized high carbon leakage risk businesses | 0.1 | Usable only in the first three years after the carbon fee takes effect |
Suppose a company's chargeable emissions before credit deductions are 12,000 tonnes. Domestic credits can deduct at most 1,200 tonnes; using only qualifying credits with a 1.2 ratio, that corresponds to 1,000 units of credits. This is an illustrative calculation derived from the regulations, not a company's actual results, and it does not include purchase costs. The example shows that "how many credit units are needed" and "how many tonnes of emissions can be deducted" are two different numbers, so purchase volumes must be worked out using the conversion ratio.
Timing and overseas credits are subject to further limits. Under Article 11 of the same regulations, applications for deduction must be submitted by the end of May each year together with credit cancellation certificates and the carbon fee filing. Article 10 provides that businesses not at high carbon leakage risk may use foreign credits recognized by the competent authority, up to 5% of chargeable emissions. Credits available on international platforms do not automatically qualify for deduction in Taiwan; recognition must be confirmed case by case. For carbon fee rates and who pays, see "What Is Taiwan's Carbon Fee? Rates, Payers and Calculation".
Uses Beyond the Carbon Fee: EIA Incremental Offsets and Carbon Neutrality
A single purchase cannot serve every purpose at once. For incremental offsets required under environmental impact assessments (EIA), go back to the specific EIA commitments and related offset rules to confirm that the project credits match the required type, quantity and timeframe; see the Ministry of Environment's explanation of domestic credit trading. Carbon neutrality claims depend on the inventory boundary, reduction results and claim guidelines: check against the Guidelines for Corporate Carbon Neutrality Claims whether residual emissions have been quantified and whether credits can be cancelled without being claimed twice.
Under the Ministry of Environment's guidelines, a company must first conduct an inventory, implement reductions and explain its residual emissions; if offsets are used, it must also cancel qualifying credits and disclose them publicly. A purchase receipt alone cannot replace these steps. So when all you have is proof of purchase, it is worth requesting the project and credit serial numbers, issuance and cancellation records, and asking the provider to explain which uses have already been claimed. Internally, keep inventory records, reduction performance and credit use records separately and reconcile them for the same period and entity, so external offsets are never recorded as the company's own reductions.
Every use of credits starts from the emissions figures themselves. Sustaihub's DCarbon supports ISO 14064-1 organizational carbon inventories and helps with data organization and calculation; formal verification is performed by a third-party body. Further reading: for how emissions are classified, see "What Are Scope 1, 2 and 3?"; for the role of credits in long-term decarbonization targets, see "What Is Net Zero? Taiwan's 2050 Pathway".
FAQ
View AllWhat are carbon credits? Does buying them give you the right to emit?
In everyday usage in Taiwan, carbon credits mostly mean reduction credits, that is, reduction outcomes recognized under a mechanism; they differ from emission allowances under a cap-and-trade system. Buying reduction credits does not allow unlimited emissions, nor can they offset charges under any scheme.
How do carbon credits differ from carbon fees and carbon taxes?
Here, carbon credits mean reduction credits that can be used under the rules; a carbon fee is a charge levied on qualifying emission sources; a carbon tax is a tax-based carbon pricing tool. The first is a credit and the other two are levy mechanisms, so their uses and costs should be compared separately.
How do you buy carbon credits in Taiwan?
Start from the intended use and enter the domestic or international trading platform via the Taiwan Carbon Solution Exchange website. Domestic credits require following the application process of the Ministry of Environment's Reduction Credit Management System and the trading platform; check eligibility, project, volume and price before trading and subsequent use.
Turn Carbon Data into an Auditable Workflow
Use DCarbon to calculate emissions with the emission factors you configure and organize activity data and supporting evidence, so inventory data stays traceable, reviewable, and ready for customer requests.
How to decide the next stepTurn the regulation or factor requirements in the article into a data checklist first. If data crosses sites or departments, or needs verification, then evaluate whether system-based management is needed.