
Taiwan Carbon Inventory: Who Must Report, 5 Stages and Verification
A carbon inventory answers two questions: where do your emissions come from, and how much is there in total? Mandatory inventories, the carbon fee and customer requests each have their own criteria, and each of the five stages (boundary, sources, calculation, reporting, verification) should leave a traceable output. Sustaihub's review of 2025 sustainability reports from 2,023 listed companies found that 45.4% listed third-party verification or assurance.
What to decide after reading If you came for emission factors, ISO 14064, CBAM, or carbon data, the next step is to check whether activity data, emission factor versions, and supporting evidence can be traced.
Table of Contents
- Organizational Inventories and Product Carbon Footprints Measure Different Things
- Who Must Do It? Mandatory Inventories, the Carbon Fee and Customer Requests Have Separate Criteria
- Boundary, Sources, Calculation, Reporting, Verification: What Each Stage Produces
- ISO 14064-1 or the GHG Protocol? Settle the Method Before Collecting Data
- Arranging Verification: Statutory Deadlines and Assurance Among Listed Companies
- In-House, Consultant or Software: Who Does What Matters More Than the Total Price
- After the Inventory: Questions That Usually Come Next
A carbon inventory (碳盤查) compiles a company's greenhouse gas emission sources, activity data and calculation results for a defined period and boundary into an emissions inventory that answers two questions: where do the emissions come from, and how much is there in total? What really sets the scope of the work is who the inventory is for. A regulator, a customer and internal management each use it differently, so the boundary, report format and verification requirements change accordingly. The sections below explain how to tell whether you are a mandatory reporter, what each of the five stages (boundary, sources, calculation, reporting and verification) should produce, and how to arrange methods and verification, so you can decide where your inventory should start and which tasks are best handed to consultants or software.
Organizational Inventories and Product Carbon Footprints Measure Different Things
A corporate carbon inventory covers the organization. The common standards are ISO 14064-1 and the GHG Protocol, which address emission sources, energy and other applicable activity data within an organizational boundary such as a company or its plants. A product carbon footprint follows ISO 14067 instead, tracing a specific good or service through its life cycle: raw materials, manufacturing, distribution, use and disposal. The first shows a company's emissions profile; the second gives the carbon data for one product. Neither can replace the other, and a company-wide total cannot be used as a product figure. When a customer writes asking for carbon data, the first thing to clarify is which of the two they need.
Who Must Do It? Mandatory Inventories, the Carbon Fee and Customer Requests Have Separate Criteria
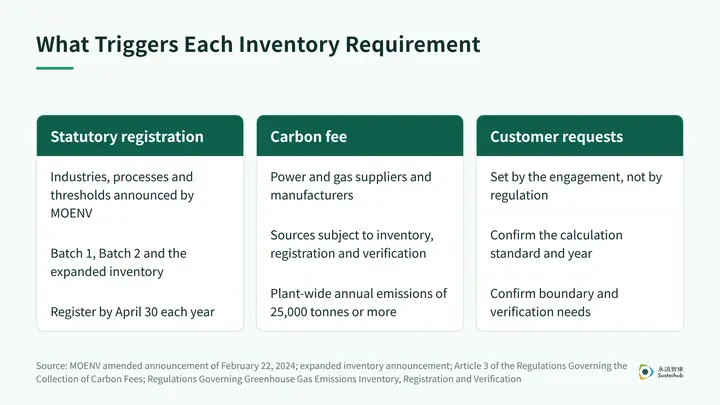
Whether a statutory inventory obligation applies depends on the industries, processes and thresholds announced by the Ministry of Environment (環境部); company size or listing status alone does not settle the question. Under the amended announcement of February 22, 2024, "Batch 1" covers designated processes such as power generation, steel, petroleum refining, cement, semiconductors and TFT-LCD, as well as emission sources whose plant-wide fossil fuel combustion emissions reach 25,000 tonnes CO₂e per year. Designated processes must also be checked against the conditions in the annex tables, so not every plant in the same industry is necessarily covered. "Batch 2", effective January 1, 2023, adds manufacturers whose direct emissions from fossil fuel combustion plus indirect emissions from electricity use reach a combined 25,000 tonnes CO₂e. The effective date can be checked against the Ministry of Environment's announcement summary; filing deadlines for past years should be read separately from the current ones.
Beyond the two batches, the expanded inventory announcement and sector guidelines also cover qualifying service businesses, transportation operators, hospitals, universities and manufacturers. These entities cannot be identified from the two batch lists alone.
The carbon fee (碳費) follows a separate set of criteria. Under Article 3 of the Regulations Governing the Collection of Carbon Fees (碳費收費辦法), fee payers are electricity and gas suppliers and manufacturers that operate emission sources announced as subject to inventory, registration and verification, and whose plant-wide direct and electricity-related indirect emissions together reach 25,000 tonnes CO₂e per year. Meeting one obligation does not mean the others apply in the same way. Customer questionnaires are different again: their requirements come from the engagement, not from regulation. When you receive one, ask the customer which calculation standard, reporting year, boundary and verification requirements they expect, so the inventory you deliver fits its purpose.
Turn this article into your next step
If this article touches disclosure, carbon inventory, or report preparation, use the system or database to check how peers handle it.
Boundary, Sources, Calculation, Reporting, Verification: What Each Stage Produces
The Ministry of Economic Affairs (經濟部) 2025 Corporate Net-Zero Action Handbook (2025 企業淨零行動手冊) describes the sequence of inventory work as boundary, sources, calculation, reporting and verification. The five steps are easy to remember; what matters more in practice is the output each stage leaves behind, because later reviews and verification will come back to these documents.
| Stage | Work to complete | Output to keep |
|---|---|---|
| Boundary: set the scope | Confirm the organization, sites and inventory period | Boundary statement, site list and responsible contacts |
| Sources: identify emission sources | Identify combustion, process, fugitive and indirect emissions under the chosen method | Equipment list, emission source list and data sources |
| Calculation: quantify emissions | Check activity data, emission factors and units, then calculate | Line-by-line calculation sheets, factor sources and original records |
| Reporting: inventory and report | Compile results, methods, assumptions and reasons for exclusions | A consistent inventory and inventory report |
| Verification: review and verify | Review internally and arrange third-party verification as required by law or contract | Correction records and applicable verification documents |
In practice, boundary setting is where errors most often occur; for the available approaches, see how to choose a boundary-setting method. Calculation is the step most often oversimplified. Under the emission factor method, the calculation can be thought of as activity data × emission factor, but fuel heating values, unit conversions and the global warming potential of each gas all affect the result. Article 4 of the Regulations Governing Greenhouse Gas Emissions Inventory, Registration and Verification (溫室氣體排放量盤查登錄及查驗管理辦法) also lists methods such as mass balance and direct monitoring, so not every emission source is handled with the same multiplication. For factor versions and the years they apply to, see emission factor versions and applicable years.
As for data responsibilities, finance supplies electricity bills and purchase records, facilities teams confirm equipment and fuel data, each site explains its data gaps, and the inventory lead finally checks years and units across the board. When every figure can be traced back to original consumption, the calculation can be reproduced, and any discussion of whether the results are high or low rests on solid ground.
ISO 14064-1 or the GHG Protocol? Settle the Method Before Collecting Data
Carrying out a carbon inventory is not the same as obtaining a certificate. ISO 14064-1 is a standard for quantification and reporting at the organizational level, and the GHG Protocol also provides methods and guidance for corporate emissions inventories. Which one you adopt depends on the purpose of the deliverable.
Statutory inventories should follow Ministry of Environment regulations and the inventory guidelines first, referring to other applicable standards only on matters the regulations do not cover; a self-selected standard cannot replace the content required for statutory registration. Where a customer or disclosure framework has additional requirements, list the standard, version, organizational boundary and reporting scope in a single requirements table and compare them item by item. Settling the method before data collection is far easier to manage than reclassifying once the results are calculated. For how the two methods can work together, see ISO 14064 vs. the GHG Protocol.
Arranging Verification: Statutory Deadlines and Assurance Among Listed Companies
Statutory inventories have two fixed deadlines. Under Articles 6, 8 and 9 of the Regulations, the previous year's inventory and report should in principle be registered by April 30 each year. Entities designated for verification must be verified by a verification body accredited by the Ministry of Environment and must upload the verification results by October 31. Case-specific applicability and any separate approvals by the competent authority follow official requirements.
Third-party verification or assurance of sustainability reports is a separate track from statutory verification, and the two should not be confused. Sustaihub reviewed the 2025 sustainability reports of 2,023 companies listed on the Taiwan Stock Exchange (臺灣證券交易所) and the Taipei Exchange (櫃買中心): 45.4% (918 companies) listed third-party verification or assurance, 25.5% (515 companies) were assured by accounting firms, and only 2 used reasonable assurance. The share was 59.9% (1,120 companies) for the 2023 reporting year and fell to 43.5% for 2024. The main reason was that the reporting obligation was extended to all listed companies, raising the number of preparers from 1,120 to 1,940, not that existing reporters dropped assurance. Note that "listed" only means the relevant field in the filing data was completed; whether assurance covers the entire report depends on each report's assurance statement.
For statutory verification and report assurance alike, self-review before submission affects how many follow-up requests you receive: Do the totals in the inventory and the report match? Can every emission source be traced to supporting documents? Does each factor state its applicable year? Is the treatment of missing data explained? After a third party issues corrections, update the inventory and the report together and keep both versions, so whoever takes over later understands why the changes were made.
In-House, Consultant or Software: Who Does What Matters More Than the Total Price
The three approaches can be combined; the difference lies in who is responsible for each part. Companies that already have an inventory method and data owners can compile the inventory themselves, provided someone is clearly responsible for checking the boundary, factors, formulas and supporting documents. When you need help determining scope or setting up a workflow, consulting support is the better fit; when comparing offers, check whether training, on-site support and document revisions are included. Software helps organize data and perform calculations, and a trial with your own data is the most reliable way to check the results and their basis. Whichever route you choose, the original data must be confirmed by the company, and formal verification is carried out by a third-party body.
When comparing prices, itemize internal staff time, consulting services, tools and third-party verification, and ask every provider to quote on the same year and the same boundary. Comparing quotes that cover different sites, data scopes or verification services by the lowest total alone is meaningless. No general timeline or fixed price is offered here; schedules should be agreed in writing based on sites, emission sources, data gaps and deliverables, with inventory completion, document corrections and third-party verification each placed on the calendar separately. For comparison criteria, see the carbon inventory software comparison.
Sustaihub's DCarbon carbon inventory system supports organizational carbon inventory automation, an AI receipt assistant, automatic route screenshots, AI-generated inventory reports and product carbon footprint calculation, aligned with ISO 14064-1 and ISO 14067. The system handles data organization and calculation, the company reviews the draft report, and formal verification is performed by a third-party body. Running a trial calculation with representative documents such as electricity and fuel bills is the easiest way to see whether it suits your data.
Further reading: to compare the timelines for sustainability reports, IFRS, inventories and the carbon fee in one place, see Taiwan Sustainability Timeline: GHG, Carbon Fee, Reports, IFRS, ESG. If your inventory request comes from a supply-chain customer, how SMEs can meet customer carbon inventory requirements explains how to deliver data the customer can actually use.
After the Inventory: Questions That Usually Come Next
Once an organizational carbon inventory is complete, companies usually move on to statutory registration deadlines, carbon fee estimates, Scope 3 data, product carbon footprints, and how to set net-zero or carbon neutrality targets. The articles below follow that order, so start with whichever question is most pressing for you.
- GHG Inventory Registration in Taiwan: Who, Deadlines and Guidelines
- What Are Scope 1, 2 and 3? The 15 Scope 3 Categories, ISO Mapping and Disclosure Trends
- What Is a Carbon Footprint? Product Footprint Calculation, Factor Lookup and Carbon Labels
- Taiwan Carbon Fee: Rates and Deductions for a 100,000-Tonne Plant
- Taiwan Carbon Credits: Trading, Prices and a 10% Carbon Fee Example
- What Is Net Zero? Taiwan's 2050 Pathway, Legislation and Corporate Targets
- What Is Carbon Neutrality? The ISO 14068 Revision and MOENV Claim Guidelines
- Taiwan Sustainability Timeline: GHG, Carbon Fee, Reports, IFRS, ESG
- ESG Glossary: Definitions and Official Sources for 27 Sustainability and Carbon Management Terms
FAQ
View AllWhat is a carbon inventory?
It compiles greenhouse gas emission sources, activity data, calculation results and supporting evidence for a defined period and boundary into an organization's emissions inventory, answering where emissions come from and how much there is in total.
Which companies are required to conduct a carbon inventory?
Check the Batch 1 and Batch 2 entities that the Ministry of Environment has designated for inventory, registration and verification, as well as the criteria in the expanded inventory announcement. Carbon fee liability is assessed separately under Article 3 of the Regulations Governing the Collection of Carbon Fees, while customer requests depend on the terms of the engagement.
What are the steps in a carbon inventory?
Work can follow five stages: boundary, sources, calculation, reporting and verification. That means setting the boundary, identifying emission sources, quantifying emissions, producing the inventory and report, and conducting an internal review plus any applicable third-party verification.
Turn Carbon Data into an Auditable Workflow
Use DCarbon to calculate emissions with the emission factors you configure and organize activity data and supporting evidence, so inventory data stays traceable, reviewable, and ready for customer requests.
How to decide the next stepTurn the regulation or factor requirements in the article into a data checklist first. If data crosses sites or departments, or needs verification, then evaluate whether system-based management is needed.