
GHG Inventory Registration in Taiwan: Who, Deadlines and Guidelines
Covered businesses must in principle register the previous year's inventory and report by April 30 each year, and those subject to verification must also upload verification results by October 31. Here is how to determine coverage, choose the right guidelines and factors, and map ISO 14064-1 Categories 1 to 6.
What to decide after reading If you came for emission factors, ISO 14064, CBAM, or carbon data, the next step is to check whether activity data, emission factor versions, and supporting evidence can be traced.
Table of Contents
- Which Type of Covered Entity Are You?
- Two Deadlines a Year: Registration by April 30, Verification Results by October 31
- Inventory Guidelines: Download the Right Documents for Your Status
- Emission Factors: Publication Date, Activity Year and Applicable Year Are Three Different Things
- How ISO 14064-1 Categories 1 to 6 Relate to Statutory Registration
- Before Submitting, the Inventory, Report and Source Data Must Support Each Other
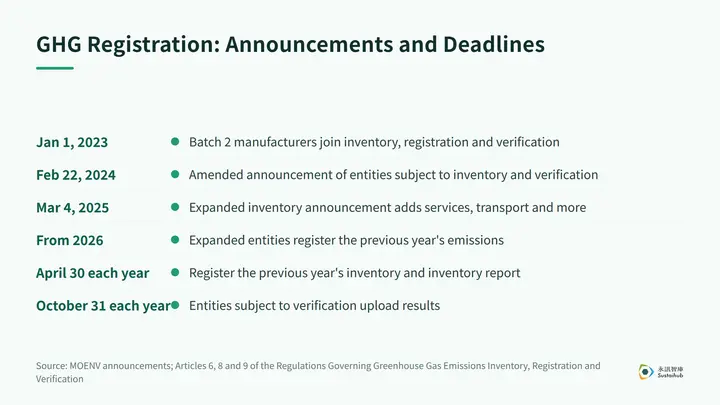
Under the Regulations Governing Greenhouse Gas Emissions Inventory, Registration and Verification (溫室氣體排放量盤查登錄及查驗管理辦法), businesses announced as subject to "inventory, registration and verification" or to "inventory and registration" must in principle register the previous year's emissions inventory and inventory report on the Ministry of Environment (環境部) platform by April 30 each year. Those designated for verification must also upload the verification results by October 31. The inventory is the compilation, calculation and analysis of emissions; registration is the submission of statutory data to the competent authority; verification is performed by an accredited body. Each is a separate obligation. The sections below cover coverage status, annual deadlines, official guidelines, factor versions and ISO 14064-1 Categories 1 to 6, to help you judge what your current inventory report still lacks before it can serve as a statutory filing. A report produced for a voluntary inventory cannot necessarily be registered as is.
Which Type of Covered Entity Are You?
Statutory obligations are determined by the announced industries, processes and thresholds; emissions volume or company name alone cannot settle the question. The original two batches are entities subject to "inventory, registration and verification", identified under the amended announcement of February 22, 2024 and its annex tables. A separate expanded inventory announcement also applies, and registration and verification duties must be confirmed separately.
| Entity | Key criteria | Required actions |
|---|---|---|
| Batch 1 | Designated processes such as power generation, steel, petroleum refining, cement, semiconductors and TFT-LCD; or plant-wide fossil fuel combustion emissions of 25,000 tonnes CO₂e or more per year | Inventory, registration and verification as specified in the announcement |
| Batch 2 | Manufacturers whose plant-wide direct emissions from fossil fuel combustion plus indirect emissions from electricity use reach a combined 25,000 tonnes CO₂e | Subject to inventory, registration and verification from January 1, 2023 |
| Expanded inventory | Check industry, energy use, number of stores or vehicles, hospital accreditation level and other conditions under the announcement | Inventory and registration; no verification is required under this announcement, and it does not by itself make a business subject to the carbon fee |
Designated processes may carry additional equipment and production conditions. The annex tables are the basis for determining coverage; the industry name is only a starting point. The effective date for Batch 2 can be checked against the Ministry of Environment's announcement summary, and filing deadlines for past years should be read separately from the current ones.
The Ministry of Environment's expanded inventory announcement of March 4, 2025 requires qualifying entities to complete inventory registration for the previous year starting in 2026. Its scope includes certain service businesses, transportation operators, hospitals, universities and manufacturers. Businesses in the same industry may reach different outcomes depending on energy use or other conditions, and entities newly covered by the announcement only need to complete inventory registration, without verification.
Two Deadlines a Year: Registration by April 30, Verification Results by October 31
Turn this article into your next step
If this article touches disclosure, carbon inventory, or report preparation, use the system or database to check how peers handle it.
The two deadlines cover different work and are based on Articles 6, 8 and 9 of the Regulations. By April 30, the previous year's emissions inventory and inventory report must be registered. For cases designated for verification, a verification body accredited by the Ministry of Environment carries out the verification, and the verification summary report, verification statement and any necessary corrections must be uploaded by October 31. If the verification results differ from what was originally registered, Article 9 requires the corrected inventory and report to be uploaded.
Statutory registration is done on the Business Greenhouse Gas Emissions Information Platform (事業溫室氣體排放量資訊平台). Account and application procedures are explained in its getting-started section, after which you enter the inventory system for your entity type. Saving a draft does not complete registration: registration is only finished once you have submitted, checked the case status, year and attachment versions, and kept a record of the submission. Under Article 14, related records must be kept for six years. Notices about individual extensions or special years follow platform announcements; neither a consultant's appointment date nor an internal sign-off date can substitute for the statutory deadline.
Inventory Guidelines: Download the Right Documents for Your Status
The "Inventory Guidelines and Calculation" section of the Ministry of Environment platform provides separate documents for the two types of entity. The inventory guidelines for entities subject to inventory, registration and verification currently offer the manufacturing edition of the GHG Emissions Inventory Guidelines (溫室氣體排放量盤查作業指引), 2024 edition (ROC year 113). The inventory guidelines for entities subject to inventory and registration separately list documents for service businesses, transportation operators, hospitals, universities and others, with manufacturers referring to the corresponding manufacturing guidelines. ROC year 113 is 2024; the year of the document is not the same as the emissions year being reported.
When reading the guidelines, the sections on scope, boundary, emission sources, data and factors, reporting and verification are the ones most worth comparing, one by one, with the data your company can provide. Where the guidelines and regulations already specify a requirement, they take precedence; for matters they do not cover, the platform notes that the latest edition of international or national standards may be referenced. Save the applicable announcement, download date and file version together when downloading, so collaborators do not end up using different inventory templates. Downloading the guidelines does not amount to a compliance determination, however; the actual industry, emission sources and filing purpose still need to be checked item by item.
Emission Factors: Publication Date, Activity Year and Applicable Year Are Three Different Things
Factors should be selected according to the inventory year, emission source and statutory calculation method; the file with the newest name is not necessarily the right one. Under Article 4 of the Regulations, the emission factor method may use factors published by the competent authority, or plant-specific factors derived from qualifying international literature or test reports; fuel combustion also involves net calorific values. When looking up a factor, record the equipment use, fuel type, gas, unit, version and source so a reviewer can find the same line of data.
A year-specific rule only answers the question for that year. The Ministry of Environment's interpretation letter of June 6, 2024 specifies version 6.0.4 factors for 2023 emissions. This neither implies that the same version applies to later years nor means every older version is prohibited; see applicable years for version 6.0.4 and published factors for details. Current documents, including the published emission factors and item-by-item notes, are available on the platform; separately check the annual calorific values, electricity emission factor and applicable interpretation letters. For data published in 2026, also check which activity year it describes; the verification approach is set out in checking the year, emission source and unit of published factors.
How ISO 14064-1 Categories 1 to 6 Relate to Statutory Registration
Categories 1 to 6 are the ISO 14064-1 classification of organizational emissions, used to distinguish direct emissions from indirect emissions of different origins. They do not use the same names as Taiwan's statutory registration fields, so completing a category table does not satisfy every filing requirement.
| Category | Meaning | How to identify |
|---|---|---|
| 1 | Direct GHG emissions and removals | Sources owned or controlled by the organization |
| 2 | Indirect emissions from imported energy | Indirect emissions from purchased energy |
| 3 | Indirect emissions from transportation | Related transportation activities outside the organizational boundary |
| 4 | Indirect emissions from products used by the organization | Emissions associated with goods or services the organization purchases and uses |
| 5 | Indirect emissions associated with the use of the organization's products | Activities related to the use of products the organization provides |
| 6 | Indirect emissions from other sources | Other indirect sources not covered by the categories above |
Category names follow ISO's official description of the six inventory categories in ISO 14064-1. Direct emissions within the organizational boundary should be quantified and reported; indirect emissions are included based on significance assessment and applicable requirements, with the rationale documented. Difficulty in obtaining data is not a reason to leave them out. For the concept of significance, see the emission source identification section of the inventory handbook published by the National Land Management Agency (國土管理署); for practical application, see how to conduct a significance assessment for carbon inventories.
Statutory inventories have a clear baseline: Article 3 of the Regulations lists direct emissions from stationary and mobile combustion, processes and fugitive sources, as well as energy indirect emissions from purchased electricity or steam. A company's own assessment that a source is "not significant" cannot override legal requirements.
Before Submitting, the Inventory, Report and Source Data Must Support Each Other
Registration centers on the emissions inventory, the inventory report and the source data that supports the calculations. Under Article 7 of the Regulations, the report covers basic information, emission sources, methods and data sources, and some non-manufacturing entities have corresponding requirements. Before submitting, use the following points as a final check:
- Are the years consistent, and are the report and inventory the same version?
- Are all covered sites included?
- Has any purchased energy been missed?
- Are the calculation units compatible?
- If verification is required, has it been scheduled?
When different departments report inconsistent consumption figures, establish the scope and period, then correct the totals. Averaging away the differences only makes verification harder to explain. Articles 7, 9 and 14 of the Regulations set out the requirements for reports, corrections and record retention; linking inventory line numbers back to bills, test results or operating records lets you locate the original evidence during corrections and verification. Sustaihub's DCarbon provides organizational carbon inventory automation, an AI receipt assistant and AI-generated inventory reports to help with data organization and calculation; the content must still be confirmed by the company, and formal verification is performed by a third-party body.
Further reading: if you are just setting up an inventory process, start with "What Is a Carbon Inventory?" for how the five stages divide the work; to find out whether covered businesses must also pay the carbon fee and how the amount is calculated, continue with "What Is Taiwan's Carbon Fee?".
FAQ
View AllWhich businesses must complete GHG inventory registration?
Determine whether you are a Batch 1 or Batch 2 entity subject to inventory, registration and verification under the amended announcement of February 22, 2024, and also check industry, energy use and other criteria under the expanded inventory announcement of March 4, 2025. Obligations are not limited to businesses emitting 25,000 tonnes or more.
When must registration be completed?
In principle, the previous year's emissions inventory and inventory report must be registered by April 30 each year. Where a separate approval or special notice applies, follow the competent authority's requirements.
Do registration and verification share the same deadline?
No. Entities designated for verification are verified by a body accredited by the Ministry of Environment and must upload the results by October 31 each year. If the verification results differ from the original registration, the corrected inventory and report must be uploaded.
Turn Carbon Data into an Auditable Workflow
Use DCarbon to calculate emissions with the emission factors you configure and organize activity data and supporting evidence, so inventory data stays traceable, reviewable, and ready for customer requests.
How to decide the next stepTurn the regulation or factor requirements in the article into a data checklist first. If data crosses sites or departments, or needs verification, then evaluate whether system-based management is needed.