
Taiwan Carbon Fee: Rates and Deductions for a 100,000-Tonne Plant
The carbon fee is not simply total emissions multiplied by a rate. A hypothetical plant emitting 100,000 tonnes CO₂e a year shows how the K value, adjustment coefficient, the NT$300 and preferential rates, and the 10% cap on reduction credits affect the amount due, along with the end-of-May payment schedule.
What to decide after reading If you came for emission factors, ISO 14064, CBAM, or carbon data, the next step is to check whether activity data, emission factor versions, and supporting evidence can be traced.
Table of Contents
- Before Calculating: Is This Plant Subject to the Fee?
- Step 1: Convert Annual Emissions into Chargeable Emissions
- Step 2: Apply the Rate to Three Scenarios
- How to Obtain a Preferential Rate: Voluntary Reduction Plan Timing
- Step 3: Deduct Domestic Reduction Credits from Chargeable Emissions
- When Is the Bill Due? Payment Schedule, First-Year Results and the Next Rate
The carbon fee (碳費) is a statutory charge levied on a business's greenhouse gas emissions after inventory, registration and verification. The current general rate is NT$300 per tonne of CO₂e, with preferential rate A at NT$50 and preferential rate B at NT$100. The amount due, however, is not "total company emissions × rate": the K value, the emissions adjustment coefficient and reduction credit deductions all sit in between. Using a hypothetical plant emitting 100,000 tonnes CO₂e a year, the sections below walk through who pays, chargeable emissions, rates, reduction credits and the payment schedule, so you can see which conditions really drive the bill. All calculations here are illustrative examples, not any company's actual fee.
Before Calculating: Is This Plant Subject to the Fee?
Taiwan's carbon fee is levied under the Climate Change Response Act (氣候變遷因應法), which was amended, promulgated and took effect on February 15, 2023. On August 29, 2024, the Ministry of Environment (環境部) issued the Regulations Governing the Collection of Carbon Fees (碳費收費辦法), the Regulations Governing the Management of Voluntary Reduction Plans (自主減量計畫管理辦法) and the Designated Greenhouse Gas Reduction Targets for Carbon Fee Payers (碳費徵收對象溫室氣體減量指定目標). Revenue goes into the Greenhouse Gas Management Fund (溫室氣體管理基金) and is earmarked for mitigation, adaptation and related work; details are available on the Climate Change Administration (氣候變遷署) carbon fee page. The carbon fee is a statutory charge on designated businesses, distinct from a "carbon tax" set through the tax system. Reduction credits are instruments that may be applied for as a deduction when the rules are met; buying credits does not automatically exempt a business from the fee.
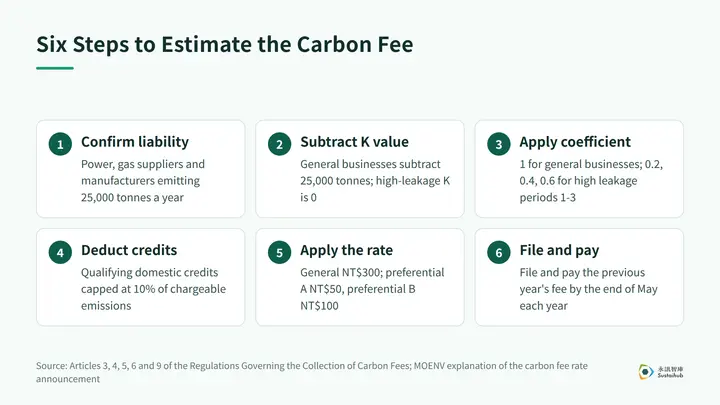
Under Article 3 of the Regulations Governing the Collection of Carbon Fees, a fee payer must meet all three conditions: it is an electricity supplier, gas supplier or manufacturer; it operates emission sources announced as subject to inventory, registration and verification; and its plant-wide direct emissions plus indirect emissions from electricity use total 25,000 tonnes CO₂e or more per year. Conducting an inventory does not by itself mean a company must pay the fee. The example plant is assumed to be a covered manufacturer with annual emissions of 100,000 tonnes, so all three conditions are met.
Businesses covered for the first time are subject to additional provisions. Article 3-1, added by the amendment of September 1, 2026, sets a separate starting point for the filing and payment obligations of businesses that meet the criteria for the first time. Those who qualify must also meet conditions such as never having reported emissions or filed and paid carbon fees for the same business or emission source, so not every new plant can decide on its own to defer. For how to organize plant boundaries and inventory data, see "What Is a Carbon Inventory?".
Step 1: Convert Annual Emissions into Chargeable Emissions
The fee is calculated not on annual emissions but on chargeable emissions. Under Articles 5 and 6 of the Regulations:
Chargeable emissions = (annual emissions − K value) × emissions adjustment coefficient
The K value and adjustment coefficient depend on whether the plant has been recognized as a business at high risk of carbon leakage. For businesses not so recognized, the K value is 25,000 tonnes and the adjustment coefficient is 1. For recognized high carbon leakage risk businesses, the K value is 0 and the adjustment coefficients for the first, second and third periods are 0.2, 0.4 and 0.6 respectively. Applied to the example plant, chargeable emissions for a general business are (100,000 − 25,000) × 1 = 75,000 tonnes; if the plant is recognized as a high carbon leakage risk business in the first period, they are (100,000 − 0) × 0.2 = 20,000 tonnes.
The high carbon leakage adjustment requires an approved voluntary reduction plan and recognition through review; companies cannot simply elect it. Article 6 also requires the application for recognition to be filed by January 31 of the payment year, and the coefficient periods should not be converted on your own into calendar years that have not been announced.
Turn this article into your next step
If this article touches disclosure, carbon inventory, or report preparation, use the system or database to check how peers handle it.
Step 2: Apply the Rate to Three Scenarios
According to the Ministry of Environment's explanation of the carbon fee rate announcement, the general rate is NT$300 per tonne. Businesses whose voluntary reduction plans are approved and that meet requirements such as the industry-specific designated reduction rate qualify for preferential rate A at NT$50; those meeting requirements such as the technology benchmark designated reduction rate qualify for preferential rate B at NT$100. Placing the example plant in three scenarios:
| Hypothetical scenario | Chargeable emissions | Rate | Estimated carbon fee |
|---|---|---|---|
| General business, general rate | (100,000 − 25,000) × 1 = 75,000 tonnes | NT$300 | 75,000 × 300 = NT$22,500,000 |
| General business, preferential rate B | (100,000 − 25,000) × 1 = 75,000 tonnes | NT$100 | 75,000 × 100 = NT$7,500,000 |
| High carbon leakage, first period, preferential rate A | (100,000 − 0) × 0.2 = 20,000 tonnes | NT$50 | 20,000 × 50 = NT$1,000,000 |
Each row assumes that the preferential rate eligibility and high carbon leakage recognition have already been obtained, and none includes reduction credit deductions or other adjustments available on application. The bill for the same plant varies widely, and the gap comes from both ends: the rate depends on the voluntary reduction plan, while chargeable emissions depend on the K value and adjustment coefficient. When budgeting, check the conditions on both ends against the official approval results.
How to Obtain a Preferential Rate: Voluntary Reduction Plan Timing
A preferential rate applies only after a voluntary reduction plan has been submitted and approved, implemented as planned and found compliant on inspection. Choosing A or B is a question of reduction pathway and designated targets, not of picking the lowest unit price when filing.
Under Article 11 of the Regulations Governing the Management of Voluntary Reduction Plans, an application filed by June 30 and one filed after that date lead to different starting years for the preferential rate: the former may apply from the year of application, subject to approval and inspection, while the latter applies from the following year. "Year" here means the year of emissions and rate application; actual payment still follows the next year's schedule.
Businesses covered for the first time that fall within Article 3-1 of the fee regulations are also subject to Article 11-1 of the plan regulations: if they submit a plan by October 31 of the year in which they complete the required inventory, registration and verification, and it is approved, they may proceed under Article 11, paragraph 1, subparagraph 1. In addition, Article 9 requires a progress report for the previous year to be submitted by April 30 each year. For how to write the plan, see the practical guide to voluntary reduction plans; application deadlines, designated targets and approval conditions follow the current official regulations.
Step 3: Deduct Domestic Reduction Credits from Chargeable Emissions
Under Article 9 of the fee regulations, qualifying domestic reduction credits may be applied to deduct chargeable emissions, up to 10% of chargeable emissions. This is a cap on the emissions deducted, not a rule that any purchase cost can be offset against the amount due, and credits are not all converted one-to-one: credits from voluntary reduction or offset projects have a deduction ratio of 1.2, while legacy early-action project credits have a ratio of 0.3 for businesses not at high carbon leakage risk and 0.1 for high carbon leakage risk businesses, and may only be used in the first three years after the fee takes effect.
Returning to the general-business scenario for the example plant, chargeable emissions are 75,000 tonnes, so the domestic credit deduction cap is 7,500 tonnes. Using only qualifying credits with a 1.2 ratio, reaching the cap would require 6,250 tonnes of credits. This is still an illustrative calculation; in practice, credit eligibility and cancellation documents must be confirmed. Under Article 11, cancellation certificates must be submitted by the end of May each year together with the carbon fee filing.
Foreign reduction credits are governed by Article 10. They are available only to businesses not recognized as high carbon leakage risk, must meet the conditions recognized by the competent authority, and are capped at 5%; not every overseas credit can be used.
When Is the Bill Due? Payment Schedule, First-Year Results and the Next Rate
Under Article 4 of the fee regulations, existing fee payers in principle file and pay the previous year's carbon fee by the end of May each year. The rate took effect on January 1, 2025. In 2025, businesses made a trial filing without payment; in 2026, the carbon fee for 2025 was paid for the first time, with the deadline moved to June 1, 2026 because of a holiday; in 2027, the 2026 fee is due by the end of May under current rules. The schedule can also be checked on the official carbon fee page.
First-year results are reported in the Ministry of Environment's press release of June 3, 2026: preliminary figures show that all 240 companies, covering 461 plants, paid in full, for a total of NT$4.97 billion; 402 plants had approved voluntary reduction plans, 64 under rate A and 338 under rate B. These are first-period statistics, not a fixed number of payers or level of revenue for future years.
As of October 2026, the current rates remain NT$300 for the general rate, NT$50 for preferential rate A and NT$100 for preferential rate B. The second-term carbon fee rate review committee was formed in March 2026, and the next rate is still pending review and formal announcement. The minutes of the rate review committee meeting of February 12, 2026 recommended phased increases with public communication beforehand, but the recommendation itself is not a new rate announcement. When budgeting, label current rates and hypothetical scenarios separately, keep following the official review status, and reconfirm the unit price, the emissions year it applies to and the payment year.
Sustaihub's DCarbon provides organizational carbon inventory automation, an AI receipt assistant and AI-generated inventory reports to help organize and calculate inventory data; formal verification is performed by a third-party body. Further reading: coverage status and registration deadlines are covered in the GHG inventory registration guide; companies exporting products to the EU can continue with the CBAM definitive period and data preparation.
FAQ
View AllWho must pay the carbon fee?
Electricity suppliers, gas suppliers and manufacturers that operate emission sources announced as subject to inventory, registration and verification, and whose plant-wide direct and electricity-related indirect emissions total 25,000 tonnes CO₂e or more per year. Businesses meeting the criteria for the first time should also check Article 3-1 of the Regulations Governing the Collection of Carbon Fees.
What are the carbon fee rates?
The current general rate is NT$300 per tonne of CO₂e, with preferential rate A at NT$50 and rate B at NT$100. Preferential rates require an approved voluntary reduction plan that is implemented as planned and passes inspection.
How is the carbon fee calculated?
Chargeable emissions = (annual emissions − K value) × emissions adjustment coefficient, multiplied by the applicable rate. General businesses have a K value of 25,000 tonnes and a coefficient of 1; recognized high carbon leakage risk businesses have a K value of 0 and coefficients of 0.2, 0.4 and 0.6 for the first, second and third periods.
Turn Carbon Data into an Auditable Workflow
Use DCarbon to calculate emissions with the emission factors you configure and organize activity data and supporting evidence, so inventory data stays traceable, reviewable, and ready for customer requests.
How to decide the next stepTurn the regulation or factor requirements in the article into a data checklist first. If data crosses sites or departments, or needs verification, then evaluate whether system-based management is needed.